After a fire, theft, or other loss, it can be difficult to remember everything you owned. A home inventory is a record that can help you estimate needed personal-property cover and support a future claim.
Start room by room
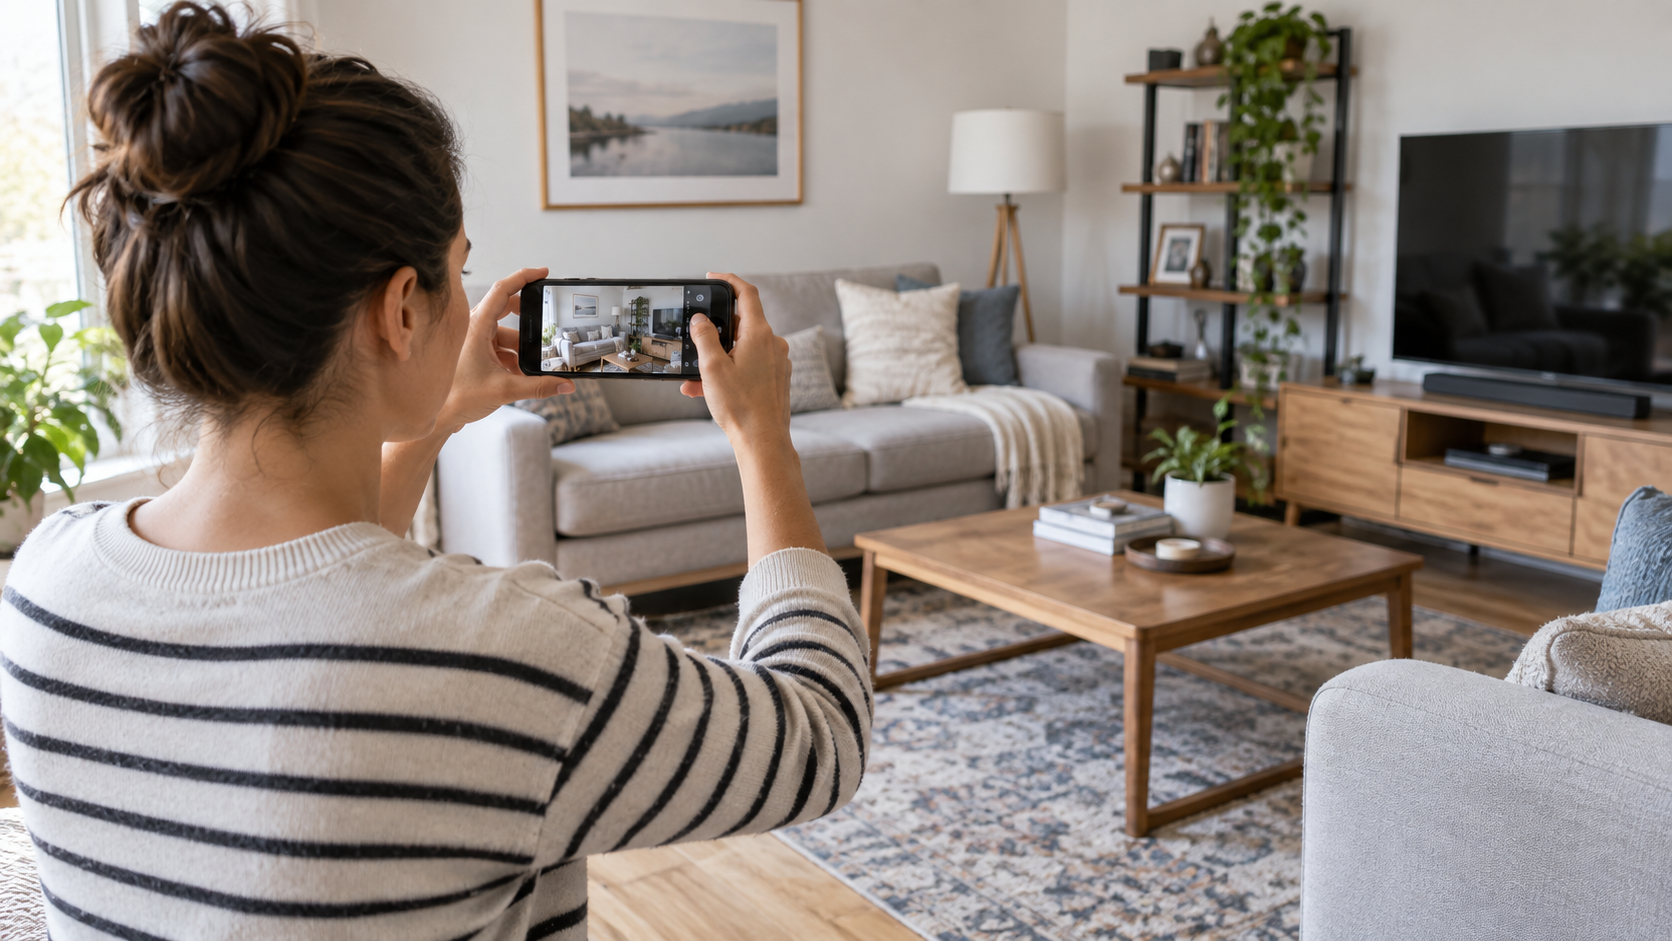
Take a slow video or clear photographs of each room, including closets, storage areas, and larger possessions. For expensive items, record a description, approximate purchase date, price if known, and serial number. Keep receipts or appraisals when available, but do not let missing paperwork stop you from starting.
Check special limits
Some policies limit payment for jewellery, electronics, collections, or business equipment. Compare your inventory with the policy’s personal-property limit and ask whether separate cover or an endorsement is needed for high-value items.
Store it safely
Keep a copy away from the home or in a secure digital account so the record survives a local loss. Protect personal details and back up the file. Update it after major purchases, gifts, renovations, or an annual review.
An inventory does not guarantee a claim payment; coverage still depends on the policy and event. It does give you a clearer, more complete starting point for conversations with your insurer.
Educational information only. Coverage, exclusions, prices, and legal requirements depend on your policy and location. Read your policy and ask a licensed professional or insurer about your situation.